Most parents-to-be figure they’ll need a few big items – a cot, a pram, maybe a car capsule – and then brace for about $100 a day once they’re back at work to pay for care. But it’s the bills that start before your baby does that dip most deeply into your bank balance. Research from NATSEM at the University of Canberra put the total cost of raising two children in a middle-income family at around $812,000 once you factor in lost income from reduced work hours. That number includes the slow leak of everyday costs most people never think to add up. This guide breaks the first year into the actual bills you’ll face, in order, so you can plan for them instead of discovering them one invoice at a time.
The First Trimester Bill Nobody Warns You About
Pregnancy tests can be inexpensive. But what follows isn’t always.
A doctor’s visit to confirm your positive test, some blood tests, and a dating ultrasound all happen in the early weeks. If you’re lucky enough to be under a full bulk-billing clinic, great. Most aren’t. You may face a gap fee at the GP, payments for specialized pathology that doesn’t fit the rebate schedule, and the imaging clinic, which needs to see you before 12 weeks. You’ll already be easily down a few hundred, likely more, before you send out a single announcement text.
The nuchal translucency scan occurs around 11-13 weeks. This optional but recommended chromosomal screening test ranges in the hundreds depending on your provider. It’s probably better to plan for these inevitable extras before reading the letter in your three-months statement and having heart palpitations.
Public Or Private: The Decision That Swings Your Budget By Thousands
The single most significant factor in your maternity budget, and one that most people don’t realise the full scale of until they’ve made their decision, is your hospital choice.
A public hospital birth, under the public system, is fully funded. There are no out-of-pocket hospital fees, no out-of-pocket obstetric fees. Your care is provided by an assigned team of midwives, and you don’t choose your obstetrician. Continuity of care varies depending on the hospital. The point is, it’s free. For a lot of families, that’s where the conversation ends.
Private care is a different equation. You choose your own obstetrician, you generally see the same doctor throughout the pregnancy, and you get a private room after the birth. The trade-off is the obstetrician gap fee – the difference between what your insurer and public rebates cover and what your specialist actually charges. These gap fees routinely land in the $3,000 to $5,000+ range across a full pregnancy, and that’s before you add the twenty-week morphology scan, which – like the NT scan – often isn’t fully rebated either.
Neither path is objectively wrong. But you need to know which one you’re budgeting for, because the financial gap between them is not small.
The Medical Costs That Sneak Up After The Big Scan
Once you’ve arrived at your delivery pathway, a second wave of costs starts to hit in the third trimester and at birth.
Anaesthetists are separate bills from the obstetrician. If you need an epidural or have a caesarean section, that’s another gap fee, usually ranging from a few hundred to over a thousand dollars depending on your insurer’s rebate and the anaesthetist’s rates. Hospital excess – the amount you pay upfront upon an admission if you have it in your policy – is another late-stage cost you’ll cop as a rookie parent, because it’s easy to overlook until you’re filling in the admission forms.
Caesareans drive costs higher on all fronts: longer hospital stay, more specialists, and a slower recovery that can lead to the parent being longer off work. A postnatal paediatrician check before discharge is also an extra that some hospitals charge for separately. None of these are avoidable if necessary, so the wise move is to overestimate the medical side of your budget rather than assume best-case.
The Waiting Period That Turns Insurance Into A Pre-Conception Decision
Here’s the detail that catches people out the most: private health insurers can deny pregnancy-related hospital claims unless you’ve held that cover for a full 12 months before conception. Not before birth – before conception.
This means the decision to take out or upgrade hospital cover for private maternity care isn’t something you make once you’re pregnant. It’s a decision that needs to happen while you’re still planning, months before a positive test. If you’re weighing up whether private obstetric care is worth the gap fees, the practical first step is checking what a policy like pregnancy health insurance actually includes and when your waiting period would start, because timing this wrong can mean paying private-level hospital costs with zero insurance contribution.
If you’re already pregnant and haven’t held cover for 12 months, private hospital birth is still possible – you’d just be paying largely out of pocket for the hospital component, on top of the obstetrician gap fees already mentioned. That’s a materially different budget to plan around.
Setting Up The Nursery Without Overspending
This is where a lot of parents overspend on things that don’t need to be expensive, and underspend on the two things that genuinely shouldn’t be bought second-hand.
A pram is the biggest single purchase, typically $300 to $1,500 depending on the brand and features. A cot and mattress set adds a few hundred more. A car seat runs $200 to $800.
Car seats and mattresses should always be bought new. Car seats have expiry dates and unknown crash histories if bought second-hand, and cot mattresses carry hygiene and safety standards that matter more than people expect. Everything else – clothing, change tables, bassinets, baby baths – is fair game for second-hand markets, and buying there can cut your one-off gear spend by half or more without any real trade-off.
The Monthly Costs That Quietly Drain Your Account
You’ll feel the nursery cost as a single hit. The consumables are where the budget seeps away from you, unnoticed, over the course of the month, until you feel like you’ve got a hole in your wallet by the end of the year.
Nappies and wipes are $60 to $100 per month for most families. Formula feeding can be an extra $40 per week, more once you move on to solid baby and toddler food. A lactation consultant is generally not covered by insurance and can cost between $100 and $200 per session; they are worth absolutely every penny if you need them, but most of us don’t think to save for that in advance.
None of these individual figures look dramatic. Added together over twelve months, they easily outstrip the one-off nursery spend.
What Government Support Gives Back
It is possible to only think about the money leaving our bank account, but what comes back the other way is also important to consider.
For instance, paid parental leave typically gives the primary carer around 26 weeks of income at minimum wage. So essentially, while you are still losing income, it isn’t as great as you may have estimated. Family tax benefits add a small but regular top-up for kids, while the fact that the government pays for childhood vaccinations means you don’t need to factor this ongoing medical cost into your forward planning.
None of this cancels out the bigger costs above. But it does mean the real out-of-pocket figure is lower than the raw sticker price of everything listed so far, and it’s worth subtracting properly rather than budgeting on worst-case numbers alone.
Childcare: The Largest Ongoing Line Item
Once parental leave ends, childcare is likely to be the biggest line item in your budget, by a truly horrifying stretch.
For context, in a major city, long day care on a full-time basis will cost between $100 and $160 per day. Full-time care across five days a week adds up to a genuinely large annual figure – often more than a mortgage repayment in some households. This is where government support really matters: depending on family income and hours worked, the childcare subsidy can cover a substantial share of that fee, sometimes up to 90% for lower-income families. The subsidy percentage drops as income rises, so it’s worth running your own numbers rather than assuming a flat rate.
Building Your Actual Baby Budget
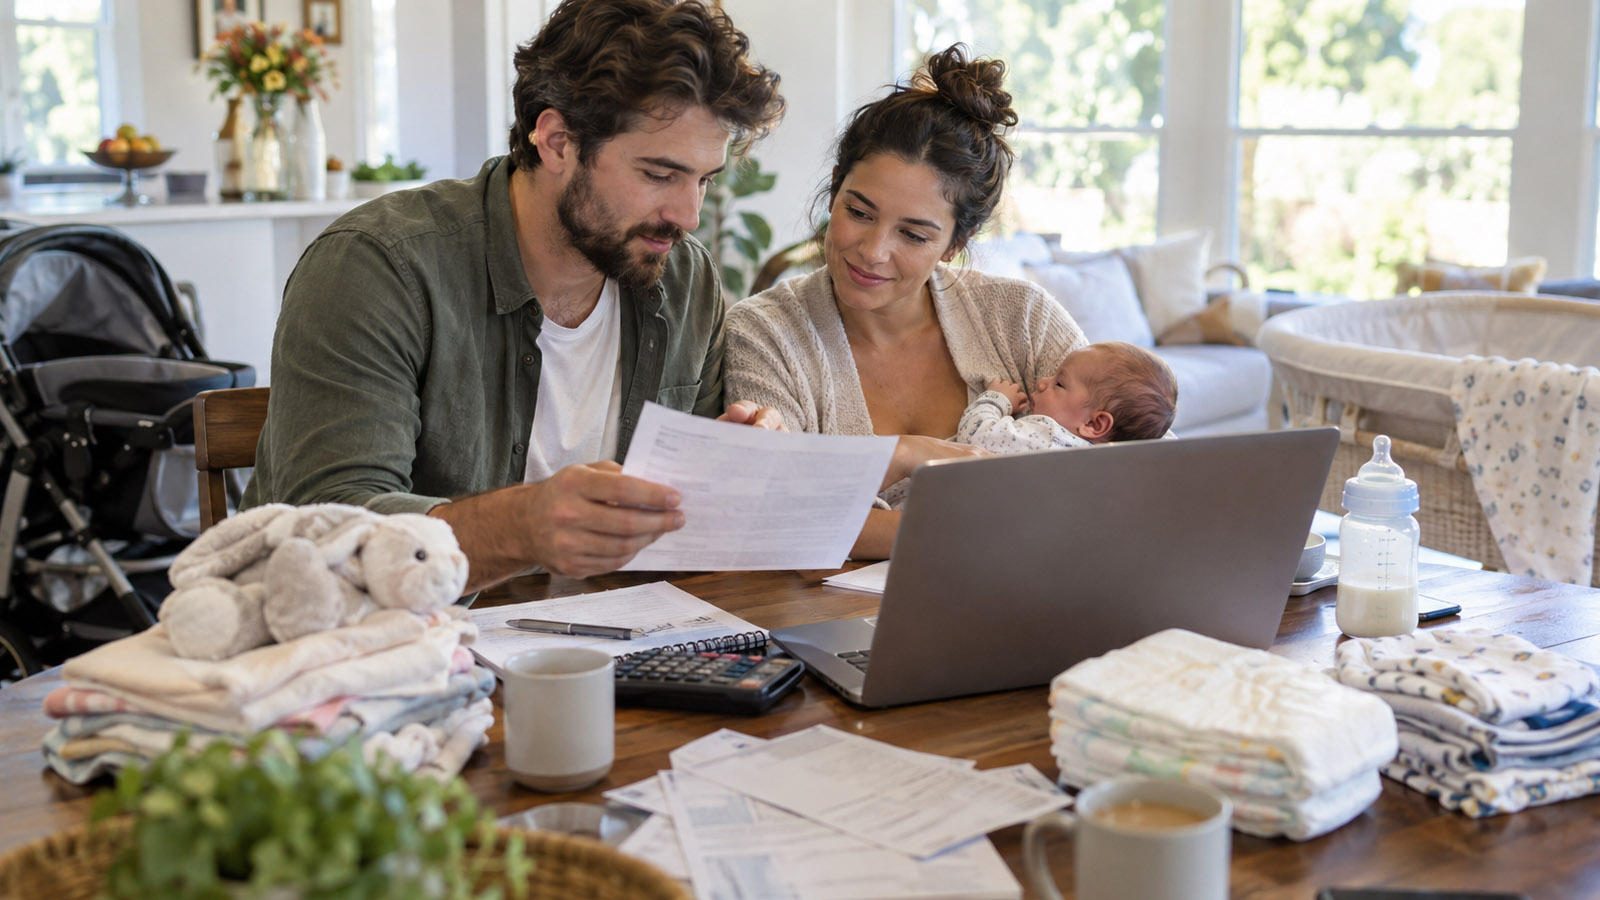
Add up your upfront medical costs – scans, gap fees, hospital excess – then your one-off gear spend, then your projected monthly consumables and, once leave ends, childcare fees. Subtract whatever parental leave pay, family benefits, and subsidies you’re eligible for. Then add a contingency buffer of 10-15% on top of the total.
That buffer matters more than it sounds. Premature birth, an unplanned caesarean, or a NICU stay can shift your numbers fast, and none of those situations are something you can predict in week eight. A cushion turns an unexpected complication into a manageable expense instead of a financial shock layered on top of everything else already going on.
The dollar figures in this guide will shift depending on where you live and which providers you use, but the structure won’t. Get the sequence right – insurance timing, delivery pathway, medical costs, gear, consumables, childcare, then subtract support – and you’ve got a budget that actually holds up once the baby arrives, rather than one that falls apart by month three.